The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Buying your first home involves more than saving a deposit. This guide explains the upfront, settlement and ongoing costs Australian first home buyers may need to budget for.
Understanding first home buyer costs in Australia can make the difference between a confident property search and a stressful settlement. Your deposit is important, but it is only one part of the budget. First home buyers may also need to allow for government charges, lender fees, inspections, legal costs, insurance, moving expenses and the ongoing cost of owning the property.
This guide explains the main upfront and ongoing expenses to consider before buying your first home. It is general information only and does not take into account your objectives, financial situation or needs. Costs, eligibility, concessions and lender requirements can vary depending on your state or territory, property type, loan structure and personal circumstances.
Why first home buyer costs go beyond the deposit
Many first home buyers start by asking, "How much deposit do I need?" That is a sensible first step, but it does not answer the full affordability question. A lender may assess whether you can service the loan, while you also need to check whether you can cover the cash required before and after settlement.
For example, two buyers with the same purchase price may face different costs if one is buying an apartment with strata levies, one qualifies for a stamp duty concession, one needs lenders mortgage insurance, or one is buying a property that needs immediate repairs.
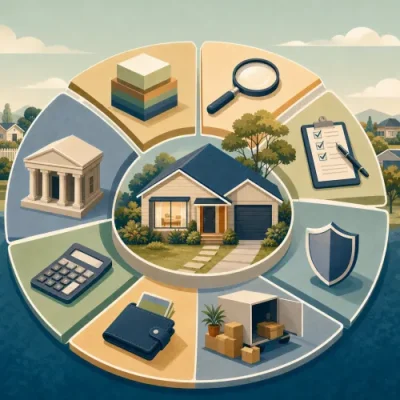
A practical first home budget should usually separate costs into three groups:
- Upfront costs paid before or around signing the contract, such as inspections and conveyancing searches.
- Settlement costs paid when the property changes hands, such as stamp duty, lender charges and settlement adjustments.
- Ongoing ownership costs paid after you move in, such as repayments, rates, insurance and maintenance.
Upfront costs when buying your first home
Upfront costs buying a first home can vary widely. Some are optional, but many are an important part of checking the property and preparing the loan application.
Deposit and savings contribution
Your deposit is the amount you contribute towards the purchase price. Many first home buyers aim for a deposit that helps reduce their borrowing amount and may reduce the chance of paying lenders mortgage insurance. However, some low deposit home loan options may be available depending on lender criteria, government scheme eligibility and your financial position.
It is important not to use your entire savings balance as the deposit if that leaves you unable to cover other buying costs or emergency expenses. Lenders may also want to see evidence of genuine savings or a consistent savings history, depending on the loan and provider.
Building, pest and strata inspections
Property inspections can help you understand what you are buying before you commit. A building inspection may identify structural issues, water damage or maintenance concerns. A pest inspection may identify termite or other pest activity. If you are buying an apartment, townhouse or villa, a strata report can help you understand the owners corporation's finances, levies, building issues and rules.
Skipping inspections can save money upfront but may expose you to larger repair costs later. The right checks depend on the property type, location, contract terms and your risk tolerance.
Conveyancing or solicitor costs
A conveyancer or solicitor can review the contract, explain legal obligations, conduct property searches and manage settlement. Their fees can depend on the property, state or territory, contract complexity and whether additional legal issues arise.
First home buyers should ask what is included in the quoted fee and what may be charged separately, such as title searches, certificates, disbursements or additional contract reviews.
Loan application, valuation and package fees
Some lenders charge application, valuation, documentation, settlement or annual package fees. Others may waive or include certain fees as part of the loan structure. The cost can depend on the lender, product, property and borrower profile.
When comparing loans, look beyond the headline interest rate. Fees, features, repayment flexibility and loan structure can all affect the total cost over time. If you are still comparing products, you may find it useful to read about first home loan options before applying.
Settlement costs first home buyers should allow for
Settlement is the point where ownership transfers to you and the purchase is completed. Several major home buying costs in Australia are usually due at or before this stage.
Stamp duty and transfer duty
Stamp duty, also called transfer duty in some states and territories, is one of the largest potential costs for home buyers. The amount can depend on where the property is located, the purchase price, whether it is a new or established home, and whether you qualify for a first home buyer concession or exemption.
Rules differ across Australia and can change over time. Some first home buyers may receive a full exemption, partial concession or other support, while others may not qualify. Always check the current rules for your state or territory before relying on a concession in your budget.
For broader information about incentives, you can read our guide to government grants and first home buyer support.
Lenders mortgage insurance
LMI for a first home buyer may apply if your deposit is below the lender's required threshold, commonly when borrowing a high percentage of the property value. LMI protects the lender, not the borrower, if the loan cannot be repaid and the lender suffers a loss after selling the property.
The cost of LMI depends on factors such as the loan amount, deposit size, lender, property type and borrower profile. It may be payable upfront or capitalised into the loan, depending on lender policy. Capitalising LMI can reduce the cash needed at settlement, but it generally increases the loan balance and may increase total interest paid over time.
Settlement adjustments
Settlement adjustments are often overlooked by first home buyers. These adjustments account for expenses the seller has already paid for a period that extends beyond settlement. You may need to reimburse the seller for your share of costs such as council rates, water rates, strata levies or land tax where applicable.
The exact adjustments are calculated as part of the settlement process and can depend on the contract and property. Ask your conveyancer or solicitor to explain the expected adjustments before settlement so you are not caught by surprise.
Registration and title fees
Government registration fees may apply when the property transfer and mortgage are registered. These are generally smaller than stamp duty but should still be included in your budget. The amount and description can vary by state or territory.
Common hidden costs when buying a house
"Hidden costs" are not always hidden in a legal sense. They are often simply costs that first home buyers do not think about until late in the process. Building them into your budget early can help reduce settlement pressure.
| Cost | Why it matters | Questions to ask |
|---|
| Moving costs | Removalists, boxes, storage and cleaning can add up, especially for interstate or long-distance moves. | Will you move yourself, hire movers, need storage or pay for end-of-lease cleaning? |
| Utility connections | Electricity, gas, internet and water account setup may involve connection or service fees. | Which services need to be connected before move-in day? |
| Immediate repairs | Even well-presented homes can need locks changed, appliances repaired, gutters cleaned or safety issues fixed. | What repairs are urgent, and what can wait? |
| Furniture and appliances | Your first home may require a fridge, washing machine, window coverings or basic furniture. | What is essential immediately, and what can be bought later? |
| Insurance | Building insurance may be required by the lender before settlement for houses. Contents insurance is separate. | What cover is required by the lender, and what cover suits the property? |
| Strata or body corporate costs | Apartments and some townhouses may have regular levies and potential special levies. | Are there planned works, disputes or levy increases? |
Ongoing expenses after buying your first home
Once settlement is complete, your budget changes from saving for a purchase to managing ownership costs. Ongoing expenses can affect your comfort level even if your loan is approved.
Home loan repayments
Your repayments will usually be one of your largest ongoing costs. Repayments depend on the loan amount, interest rate, loan term, repayment type and whether the loan is fixed, variable or split. Your repayments may change if interest rates change, your fixed rate period ends, or your loan reverts to a different rate.
Before applying, it can help to test different repayment scenarios rather than relying on one estimate. You can use the site's home loan calculators to explore how repayments may change under different assumptions.
Council rates, water and utilities
Home owners are generally responsible for council rates and water charges, although the way charges are billed varies. You will also need to budget for electricity, gas where applicable, internet and other household services.
If you are moving from a share house, family home or rental with utilities included, these costs may be higher than expected. Reviewing recent bills for similar properties can help, although your usage and provider pricing may differ.
Insurance
Building insurance covers the structure of the home and is commonly required by lenders for houses. If you buy into a strata scheme, building insurance may be arranged through the strata, but you may still need contents insurance and should understand what the strata policy does and does not cover.
Some buyers also consider income protection, life insurance or other personal insurance when taking on a large debt. Whether these are appropriate depends on your circumstances, existing cover and budget. Consider seeking licensed advice if you need personal recommendations.
Maintenance and repairs
Unlike renting, home ownership means you are responsible for most repairs and maintenance. This can include plumbing, electrical work, roof repairs, appliance replacement, garden maintenance and general wear and tear.
A useful approach is to maintain a separate buffer for repairs and unexpected expenses. The right amount depends on the age, condition and type of property, as well as your income stability and other financial commitments.
Strata levies and special levies
If you buy a strata property, regular levies contribute to shared building expenses, insurance and maintenance. Special levies may be raised for major works or unexpected costs. A strata report can help you identify existing issues, but future levies can still arise.
Do not compare an apartment and a house on purchase price alone. Strata levies, facilities, building age and maintenance obligations can change the long-term cost picture.
How grants and concessions can affect your cost budget
First home buyer grants, schemes and stamp duty concessions can make a meaningful difference, but they should be treated carefully in your budget. Eligibility can depend on location, property value, whether the home is new or established, residency requirements, occupancy rules and other criteria.
Some assistance may reduce the cash you need at settlement, while other support may be paid after certain conditions are met. If you assume you qualify and later discover you do not, your purchase budget may be short.
Before signing a contract, check the current requirements for your state or territory and confirm how any grant, concession or scheme interacts with your loan application. A broker, conveyancer, solicitor or relevant government source may help you understand the process, but eligibility and approval depend on the applicable rules and provider criteria.
Questions to ask before making an offer
Before you make an offer or bid at auction, it is worth checking whether your budget covers more than the advertised price. Useful questions include:
- How much cash will I need for the deposit, stamp duty, legal costs and settlement adjustments?
- Could LMI apply, and how would it affect my upfront costs or loan balance?
- Have I allowed for inspections, moving costs, insurance and utility connections?
- What will my repayments look like if rates change or my fixed period ends?
- Can I still manage bills, repairs and personal expenses after settlement?
- Am I relying on a grant or concession, and have I checked the current eligibility rules?
- Do I understand the costs of this property type, such as strata levies or maintenance?
If you want help checking how these costs fit with your loan readiness, you can speak with a mortgage broker for first home buyers. A broker can explain lender requirements and possible loan structures, although loan availability, pricing and approval will depend on your circumstances and lender criteria.
A simple first home buyer cost framework
A realistic first home budget does not need to be complicated. Start with the purchase price you are considering, then build a separate estimate for each cost category.
- Purchase contribution: deposit, any savings you plan to use and any confirmed support you may receive.
- Government and settlement costs: stamp duty or transfer duty, registration fees and settlement adjustments.
- Professional and due diligence costs: conveyancing, contract reviews, building, pest and strata checks.
- Lender-related costs: application fees, valuation fees, package fees and possible LMI.
- Move-in costs: removalists, cleaning, utility connections, locks, furniture and essential appliances.
- Ongoing costs: repayments, council rates, water, utilities, insurance, strata levies and maintenance.
- Safety buffer: money kept aside for unexpected costs after settlement.
This framework can help you compare properties more clearly. A cheaper property with high strata levies or urgent repairs may not be cheaper in practice. A property with a higher purchase price may also have higher stamp duty, repayments and insurance costs. The right budget depends on your income, expenses, savings, risk tolerance and long-term plans.
Final thoughts
First home buyer costs in Australia include much more than the deposit. Stamp duty, LMI, conveyancing, inspections, lender fees, settlement adjustments, insurance, moving expenses, repayments and maintenance can all affect your readiness to buy.
Before you commit to a property, build a full upfront and ongoing cost estimate and test how comfortable it feels under different scenarios. Taking time to understand the numbers can help you make a more informed decision and have more productive conversations with lenders, brokers and legal professionals.
Published: Monday, 7th Sep 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.